Log in
Get started
Credit-backed loans

A decision in principle is a maybe. This is an offer.

With participating lenders on Broka, the credit work and valuation are done up front. Your client gets a fully underwritten offer, subject only to legals.
Offered by selected lenders on suitable cases. A credit-backed offer is fully underwritten and subject to standard legal completion. It is not a guarantee of funding.

The usual route

Decision in principle

  • Valuation booked after terms
  • Underwriting still to come
  • Can fall over late in the case

Credit-backed offer

A real offer, not a maybe.

  • Valuation factored in up front
  • Credit underwriting already done
  • Subject only to legals
7 days
to complete, with legals in 72 hours. A typical bridge takes around six weeks.

Watch · 0:46

A DIP is not an offer

Why a decision in principle often gives false hope, and how a credit-backed loan is different.

In the glossary: Decision in principle, Credit-backed offer

With Kristian Wilkinson, Managing Director, Broka
0:46
The numbers

Weeks become days.

A typical bridge completes in around six weeks. With participating lenders, credit-backed cases can be into legals in 72 hours and complete within seven days.
72 hours
from application to legals with participating lenders
7 days
to complete on suitable cases
53
lenders on Broka offer dual-representation legals on bridging
55
bridging lenders on Broka offer AVM or desktop valuations
Timings apply to suitable cases with participating lenders and are not guaranteed. Lender figures from the Broka Brief, August 2026.

Watch · 2 minutes

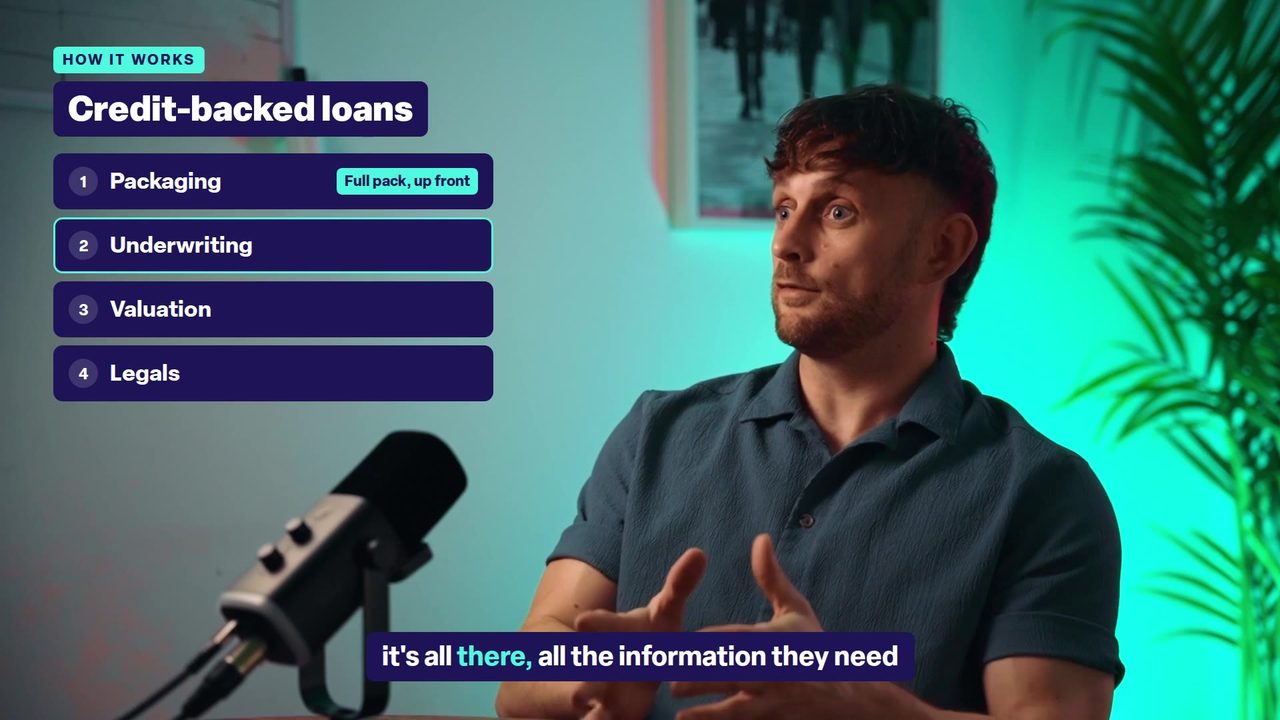
How credit-backed loans work

Where a normal bridge slows down, and how participating lenders shorten each stage.

  1. Package once. The full pack goes in up front, so the underwriter can decide in hours.
  2. Value quickly. A desktop valuation, an AVM or an in-house surveyor, rather than waiting weeks.
  3. Into legals within 72 hours. Some lenders offer dual representation, so one firm acts for both sides.

Timings apply with participating lenders on suitable cases.

In the glossary: AVM, Desktop valuation, Dual representation
2:03
How it works

The hard part happens first, not last.

You do the work you would do anyway, earlier. The lender does theirs before the offer, not after it.
  1. STEP 01

    Create the case on Broka

    Enter the case and match it. Lenders offering credit-backed on that case type are flagged in your results.

    Minutes
  2. STEP 02

    Send the full pack

    The lender’s mandatory list goes in up front: an assets and liabilities statement (A&L), ID, a bank statement and proof of address, plus the auction pack for auction purchases, a business-use declaration and sometimes a business plan. You can’t apply until it’s uploaded.

    Up front, not later
  3. STEP 03

    Lender underwrites

    Credit and valuation are completed before the offer is issued. With participating lenders that can take hours, not weeks.

    Before the offer
  4. STEP 04

    Your client gets an offer

    A fully underwritten offer, subject only to standard legals. Then it goes to completion.

    Legals in 72 hours

Same case, two routes

Typical bridgeOffer first, checks after
DIPValuationCreditOfferLegals
~6 weeksto complete
Credit-backed on BrokaChecks first, then the offer
Offer + legals
7 daysto complete

With participating lenders on suitable cases. Timings depend on the case, the borrower and the legals.

Is it right for this case?

Which cases suit credit-backed.

A quick guide. The lender has the final say on every case.

Usually a good fit

Usually better as a standard application

For lenders

Offer credit-backed on Broka.

Brokers can filter for credit-backed options. Lenders who underwrite up front stand out when a broker needs certainty.

For lenders · 0:59

Credit-backed loans: the new standard

Why Kristian thinks credit-backed loans will become the new standard, and why faster underwriting wins the business.

With Kristian Wilkinson, Managing Director, Broka
0:59

Questions about credit-backed.

How fast is it?

With participating lenders, suitable cases can be into legals in 72 hours and complete within seven days. It still depends on the case, the borrower’s documents and the solicitors.

Why can some lenders move this quickly?

They remove the usual waits. On Broka, 55 bridging lenders offer AVM or desktop valuations and 53 offer dual-representation legals (Broka Brief, August 2026).

Is a credit-backed offer guaranteed?

No. It is fully underwritten and subject to standard legal completion. It is not a guarantee of funding.

Which lenders offer it?

Selected lenders on suitable cases. When you search a case on Broka, the lenders offering credit-backed loans are shown in your results.

Does it cost my client more?

Not necessarily. Each lender sets its own pricing based on the case. You can compare credit-backed and standard options side by side in your search results before you apply.

What do I need to send up front?

The full pack goes in before underwriting: an assets and liabilities statement (A&L), ID, a bank statement and proof of address, plus the auction pack for auction purchases, a business-use declaration and sometimes a business plan. You can’t apply until the mandatory list is uploaded.

FAQ · Watch the answer · 1:06

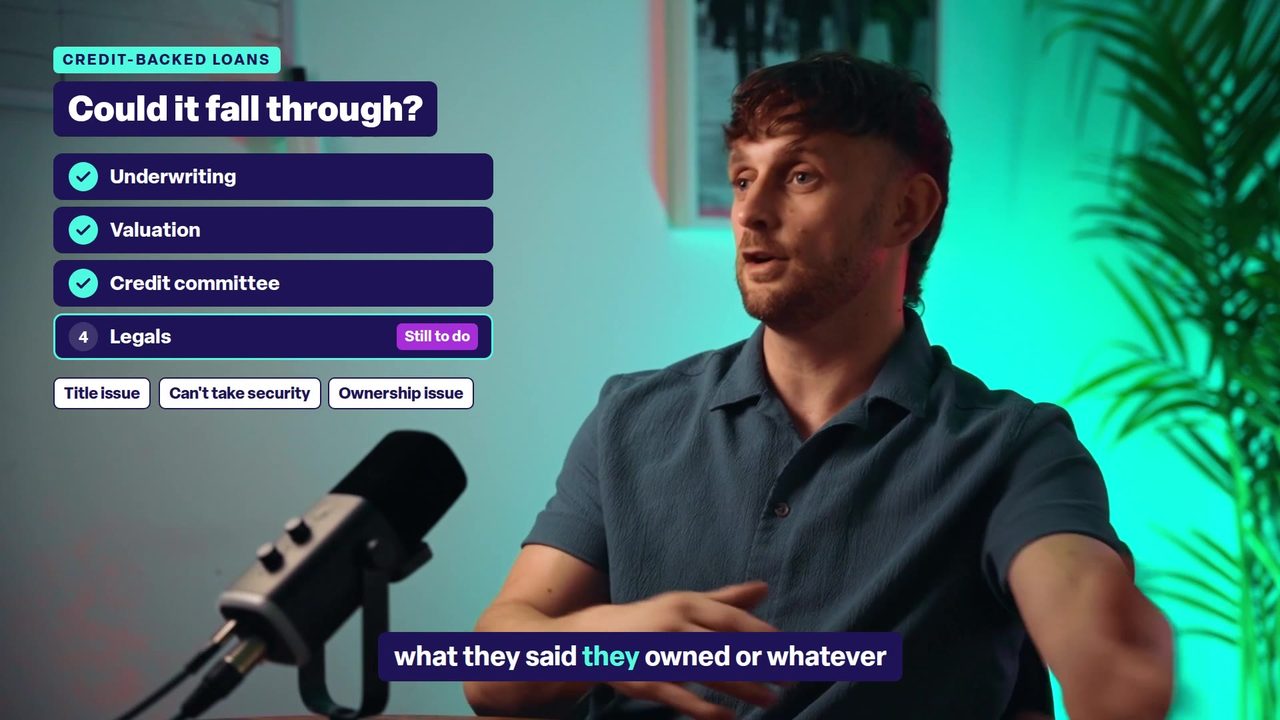
Can a credit-backed loan still fall through?

The underwrite and valuation are already done, so it is only subject to legals. Kristian explains what can still come up.

With Kristian Wilkinson, Managing Director, Broka
1:06

Run your next case as credit-backed.

Book a demo and bring a live case. We will show you which participating lenders it matches.